How Your Toronto Postal Code Affects Your Car Insurance Premiums
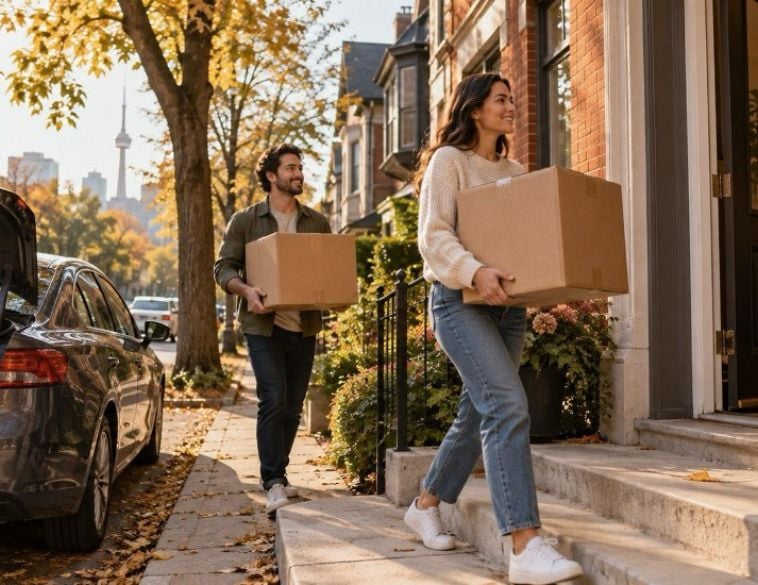
Insurers group vehicles into rating territories with custom boundaries, meaning even neighboring cars with similar postal codes can see different rates.
An insurer uses a Toronto address to place the car in a rating territory and assess local claims. A move can therefore change the price even when the car and driving record stay the same, with no new tickets or collisions. The postal code is only part of that calculation. A different commute or overnight parking place can change it too, so a new address alone won’t explain the whole difference.
Postal codes and rating territories
Insurers use an address to place a vehicle in a rating territory. A territory is an area the company uses when setting prices. Its boundaries don’t have to match the neighbourhood’s boundaries. Cars whose postal codes share the same first characters don’t necessarily get the same price.
For Toronto car insurance rates, the company also considers the vehicle, listed drivers, driving history, yearly distance, and coverage. Two neighbours can pay different amounts even if the insurer puts them in the same territory.
Insurers can group addresses differently. Ontario’s regulator approves how companies use territories. Its current testing framework allows companies that take part to try different ways of grouping them. A claim about a fixed number of Toronto territories may describe an older system. It shouldn’t be assumed to explain a current quote.
A short move can cross a territory boundary. Two homes farther apart may be in the same territory. The distance between addresses doesn’t guarantee how their quotes will compare. Nor does the postal code give the insurer a judgment about one person’s driving skill. It shows where the car is based.
The company should identify the address it used and explain whether a move changes the territory. That gives the applicant a specific answer about the car, without assuming an entire neighbourhood always costs more.
A list of cheap postal codes can’t predict the result for every applicant either. The quotes behind it may use one car and one driver, or come from a different point in time. Another person asking today may receive a different price.
What local claims tell an insurer
A driver brings their own record to the application. The insurer also considers where the car is kept. A clean record doesn’t make the address irrelevant. Living in an area with fewer claims doesn’t remove a collision or conviction from the driver’s record either.
Local conditions can affect different parts of the policy. Traffic and intersections affect the chance of a crash. Theft and damage to parked cars can lead to other kinds of claims. The cars insured in an area, and the company’s own claims records matter too.
Insurers use both local claim numbers and costs to assess an area’s risk.
Many claims can make an area costly to insure. A smaller number of expensive claims can do that too. The insurer can take those costs into account before a particular driver has made a claim there.
That approach has faced criticism. In a 2019 debate about proposed changes to Ontario’s rate setting, personal injury lawyers questioned what postal-code pricing meant for people with clean records. The debate didn’t prove that Ontario had abolished geographic pricing. A driver still needs to check the company’s current rules when asking about a quote.
A move changes more than the address
Moving farther from work may mean driving more kilometres each year. Living closer to transit may mean fewer regular car trips. A driver may also switch from a driveway to a shared garage or street parking. The application needs to reflect those changes.
If several answers change at once, the new price won’t show the postal-code effect on its own. The insurer may explain which details changed its calculation. It may not be able to give each one a separate dollar amount.
Insurance is part of the full cost of keeping the car. Toronto cost-of-living research counts car payments, insurance, fuel, maintenance, and parking.
Paying less for insurance may not save the household money if parking costs more or the commute grows longer.
A study of housing and commuting costs in the Greater Toronto Area found that travelling farther could offset savings on a home farther from work. Its old dollar figures aren’t a budget for a move today. The point is that paying less for housing can mean paying more to keep and use the car.
Insurance quotes belong beside those other costs when the household works out what the move will cost.
Which address belongs on the policy
The company needs to know where the driver lives and where the car is normally kept. A friend’s address isn’t an acceptable replacement because it produces a lower price. Incorrect details can cause problems with the policy and a later claim.
A driver who splits time between homes should explain that to the insurer. The same applies to a student keeping a car near school for much of the year. Sometimes the mailing address differs from the place the car is parked overnight. The company should explain how to record those facts, so the applicant doesn’t have to guess.
If the postal code changes while the physical address stays the same, the insurer should check its records. A correction to the code doesn’t necessarily mean the car has moved.
Checking a quote before moving
A quote at the proposed address can help before the driver chooses a home. Keeping current coverage limits and deductibles makes the prices comparable, while real changes in commute, yearly kilometres and parking need to be recorded. The old and new details also give the insurer something specific to explain if the gap looks wrong. Once the move is confirmed, the policy must describe where the car is kept and how it is used, with the new details and their effective date reported to the insurer.
Tags : Toronto car insurance rates

JOBS
 |  LAVAL  Full time |
 | BROSSARD Full time |
 | RIVE-NORD DE MONTRÉAL Full time |
 | REPENTIGNY Full time |
 | BOISBRIAND Full time |